MARY GUAN FINANCIAL · TORONTO

路遥知马力时间见证信任

Trust takes time.We plan for the long term.

为个人、家庭及企业主提供保险与财务规划相关服务。以长期利益为中心,兼顾家庭保障、退休投资、企业主财富与传承,让每一步选择更清楚。

Insurance and financial planning-related services for individuals, families and business owners. A long-term perspective connects family protection, retirement, investment considerations, business wealth and legacy.

服务安大略省客户 · 普通话沟通
Serving clients across Ontario · Mandarin-speaking service
以您的实际需求为起点Your needs come first清晰沟通,理解选择Clear conversations持续检视,长期服务Ongoing reviews & service
FOR BUSINESS OWNERS

企业的今天,也连接家庭的明天。

Your business today. Your family’s tomorrow.

企业主财富规划是我们的重点之一。结合经营需要与家庭目标,先讨论税务效率,再看长期财富积累与保障,最后协调传承。

Business owner planning is one of our areas of focus. Start with tax efficiency, consider long-term wealth accumulation and protection, then coordinate legacy goals.

  1. 税务效率
  2. Tax Efficiency
  3. 长期财富积累与保障
  4. Long-Term Wealth Accumulation & Protection
  5. 财富传承
  6. Wealth & Legacy Transfer
了解企业主规划 ↗Explore business owner planning ↗
01 / OUR SERVICES

为个人、家庭与企业主规划

Planning for individuals, families & business owners

从家庭保障、退休与投资,到企业主财富、传承、旅游保险及员工福利,先了解需要,再讨论选择。

From family protection and retirement to business wealth, legacy, travel insurance and employee benefits: understand the need before considering a product.

01

家庭保障规划

Family Protection

让保障与家庭责任、收入及未来变化相匹配。

Align protection with family responsibilities, income and changes ahead.

查看规划重点Explore planning considerations
  • 年轻家庭的收入保障、房贷及子女教育责任;人寿及重大疾病保障需求。
  • Income protection, mortgage and education responsibilities for young families; life and critical illness coverage needs.
  • 比较定期与终身保险的适当组合,兼顾高资产家庭的长期保障需求。
  • Consider an appropriate mix of term and permanent insurance, including long-term protection needs of families with substantial assets.
  • 检视现有保单、保障缺口及长期保费负担,结合家庭现金流评估。
  • Review existing policies, coverage gaps and long-term premium affordability alongside household cash flow.

不仅看今天能否支付,也考虑收入下降、职业变化、经济周期及退休后的财务状况。保障、费用及理赔条件以合同为准。

Affordability today is only a starting point. Consider lower income, career changes, economic cycles and retirement finances. Coverage, costs and claims are subject to contract terms.

预约咨询 ↗Book a Consultation ↗
02

退休与投资规划

Retirement & Investment Planning

把积累、提款与退休收入放在同一幅长期规划中。

Bring accumulation, withdrawals and retirement income into one long-term view.

查看规划重点Explore planning considerations
  • RRSP、TFSA及其他投资账户规划,结合投资目标、期限、风险承受能力和风险意愿讨论资产配置与投资组合。
  • Discuss RRSPs, TFSAs and other investment accounts, asset allocation and portfolio considerations in light of goals, time horizon, ability and willingness to take risk.
  • 不单凭年龄判断风险承受能力;同时考虑收入、资产负债、资金用途及承受损失的能力。
  • Age alone does not determine risk tolerance. Income, assets, liabilities, intended use of funds and capacity for loss also matter.
  • RRSP转RRIF、退休提款、现金流及税务因素。RRSP最迟须于年满71岁的日历年度12月31日前按规定办理到期安排,可考虑RRIF、符合规定的年金或提款,税务处理各不相同。
  • Plan RRSP-to-RRIF transitions, withdrawals, cash flow and tax considerations. By December 31 of the year you turn 71, your RRSP must be dealt with under the maturity rules, such as a RRIF transfer, eligible annuity purchase or withdrawal, with differing tax consequences.
  • 年金可为适合的客户提供合同约定的定期收入。付款可能包含本金返还,支付比例不等于投资回报率;需评估流动性、通胀、费用及合同选项。
  • Annuities may provide suitable clients with contractually specified periodic income. Payments may include returned capital; a payout percentage is not an investment return. Consider liquidity, inflation, costs and contract options.
  • 检视现有永久人寿保险在退休规划中的潜在作用。提款可能减少现金价值及保障并产生税款;保单贷款涉及利息及潜在税务后果;抵押融资须经贷款机构审批,涉及利率、还款及抵押品风险。
  • Review the potential role of existing permanent life insurance. Withdrawals may reduce cash value and coverage and trigger tax; policy loans involve interest and possible tax consequences. Collateral borrowing requires lender approval and involves interest-rate, repayment and collateral risks.

贷款并非保证可获得的退休收入来源。投资会波动,可能发生损失。

Borrowing is not a guaranteed source of retirement income. Investments fluctuate and losses are possible.

预约咨询 ↗Book a Consultation ↗
03

企业主财富规划

Business Owner Planning

兼顾企业经营与家庭未来,依次讨论税务效率、长期财富及传承。

Connect business needs and family goals through tax efficiency, long-term wealth and legacy planning.

查看规划重点Explore planning considerations
  • 第一 · 税务效率:结合企业留存收益、长期资金安排及符合条件的公司持有人寿保险,配合税务专业人士分析可行方向。
  • 1 · Tax Efficiency: Consider retained earnings, long-term funds and eligible corporate-owned life insurance arrangements with a qualified tax professional.
  • 第二 · 长期财富积累与保障:评估公司持有的分红型终身人寿保险可能发挥的长期作用,同时考虑企业流动性、经营需求、保费可持续性与早期退保成本。分红不保证。
  • 2 · Long-Term Wealth Accumulation & Protection: Assess the possible long-term role of corporate-owned participating whole life insurance alongside business liquidity, operating needs, sustainable premiums and early surrender costs. Dividends are not guaranteed.
  • 第三 · 财富传承:讨论企业接班、家庭传承,以及符合条件时保险身故赔偿与资本红利账户(CDA)的作用。CDA增额通常涉及身故赔偿减保单调整后成本基础及适用调整;支付资本红利须符合资格、账户余额和申报选择要求。
  • 3 · Wealth & Legacy Transfer: Discuss succession, family legacy and the potential role of death benefits and the capital dividend account (CDA). A life-insurance CDA credit generally reflects death proceeds less policy adjusted cost basis and applicable adjustments. Capital dividends depend on eligibility, account balance and required elections.

适合探讨此方向的企业主通常有持续盈利、适当留存收益,以及长期资金或传承需求;不设置营业收入门槛。税务递延不等于无条件免税,公司资金不能无条件免税转给个人或下一代。具体结构与税务判断须由合资格专业人士审阅。

This discussion may suit owners with ongoing profitability, appropriate retained earnings and long-term funding or legacy needs; no revenue threshold is assumed. Tax deferral is not unconditional tax exemption. Corporate funds cannot be transferred unconditionally tax-free to individuals or the next generation. Qualified professionals must review structures and tax implications.

预约咨询 ↗Book a Consultation ↗
04

财富与遗产传承

Wealth & Legacy Planning

让保险、投资合同与家庭传承意愿相互协调。

Coordinate insurance, investment contracts and your wishes for the next generation.

查看规划重点Explore planning considerations
  • 检视人寿保险受益人安排,并与遗嘱及保险、投资合同的受益人指定协调;遗嘱起草及法律判断交由法律专业人士处理。
  • Review life insurance beneficiaries and coordinate wills with insurance and investment contract designations. Will drafting and legal opinions belong with qualified legal professionals.
  • 比较Segregated Funds(分离基金保险合同)与Mutual Funds(共同基金)的合同性质、费用、投资风险及流动性。前者可提供合同规定的身故及到期保证,共同基金通常不提供这些保险保证。
  • Compare segregated fund insurance contracts and mutual funds: legal structure, fees, investment risk and liquidity. Segregated fund contracts may include contractual death-benefit and maturity guarantees; mutual funds generally do not provide those insurance guarantees.
  • 保证比例、期限及条件取决于合同;提款或其他交易可能调整保证金额,并非所有时间都可全额保本。
  • Guarantee levels, terms and conditions depend on the contract. Withdrawals and other transactions may adjust guaranteed amounts; full capital protection is not available at all times.
  • 有效受益人指定及适用法律可能带来遗产认证(Probate)方面的便利;债权人保护(Creditor Protection)仅可能在特定条件下适用,不能保证。
  • Valid beneficiary designations and applicable law may offer probate-related advantages. Creditor protection may apply only in specific circumstances and is not guaranteed.

与客户的法律及税务专业人士协作。本公司不提供遗嘱起草或法律服务,不保证避免全部遗产认证费用或获得债权人保护。

We work alongside clients’ legal and tax professionals. We do not draft wills or provide legal services, or guarantee avoidance of all probate costs or creditor protection.

预约咨询 ↗Book a Consultation ↗
05

旅游保险

Travel Insurance

出行前了解保障条件,让旅行安排更清楚。

Understand coverage conditions before you travel.

查看规划重点Explore planning considerations
  • 通过JF Insurance Agency Group Inc.联系旅游保险服务;根据具体可用产品讨论访加、留学或外出旅行需求。
  • Travel insurance service through JF Insurance Agency Group Inc.; discuss visitor, student or outbound travel needs according to available products.
  • 关注受保资格、保障期间、紧急医疗定义、既往病症及稳定期、除外责任、自付额和理赔程序。
  • Review eligibility, coverage period, emergency medical definitions, pre-existing conditions and stability periods, exclusions, deductibles and claims procedures.

不是所有医疗费用或旅行风险都受保。实际承保公司、保障范围、保费及条款须在申请前确认;健康资料仅通过适当的保险申请渠道提交。

Not all medical costs or travel risks are covered. Confirm the actual underwriter, coverage, premium and policy terms before applying; submit health information only through appropriate insurance application channels.

预约咨询 ↗Book a Consultation ↗
06

团体员工福利保险

Group Benefits

在员工保障、企业预算与长期负担能力之间取得平衡。

Balance employee protection, business budgets and long-term affordability.

查看规划重点Explore planning considerations
  • 讨论团体福利如何支持员工吸引、留任、满意度与企业竞争力。
  • Discuss how benefits can support recruitment, retention, employee satisfaction and business competitiveness.
  • 评估可用的团体医疗、牙科、人寿及伤残保险,与员工构成和保障需求匹配。
  • Assess available group health, dental, life and disability insurance in relation to your workforce and protection needs.
  • 讨论雇主与员工的保费分担、企业福利成本、适用税务处理与现有计划检视。
  • Review employer–employee premium sharing, benefit costs, applicable tax treatment and existing plans.

保费能否扣除及员工福利是否应税,取决于福利类型、付款安排和适用规则;不笼统承诺全部可抵税或免税。

Deductibility and employee taxation depend on benefit type, payment arrangements and applicable rules; no blanket deduction or tax-exemption claim is made.

预约咨询 ↗Book a Consultation ↗

合作保险公司 | Insurance Providers

Insurance Providers

马力金融通过现有业务合作渠道,为客户提供来自多家保险公司的产品选择,包括:

Mary Guan Financial works through established business relationships to offer insurance solutions from multiple insurers, including:

Canada Life · Sun Life · Manulife · iA Financial Group · Equitable Life

我们根据客户的保障需求、财务目标及实际情况,协助评估适合的保险解决方案。具体产品及服务以适用的业务授权和保险公司条款为准。

We help clients evaluate insurance solutions based on their protection needs, financial goals, and individual circumstances. Product availability and services are subject to applicable authorizations and insurer terms.

MEET MARY
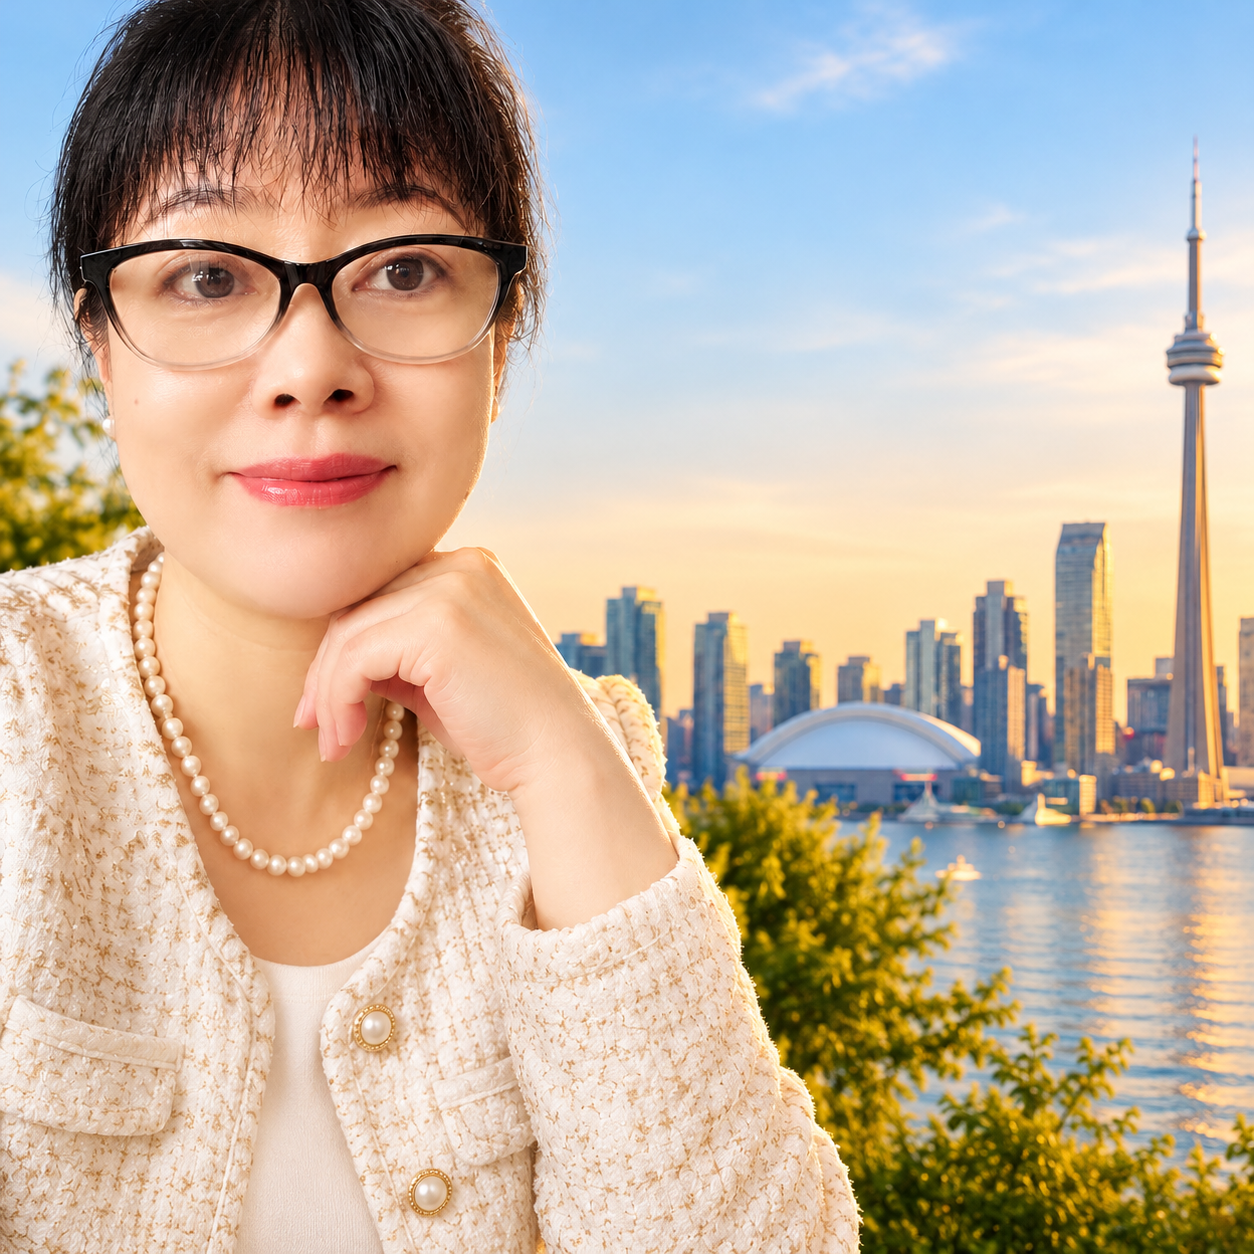
Mary Guan · 多伦多背景人像 / Toronto portraitXiaolan (Mary) Guan

Director | Licensed Life Insurance Agent

02 / ABOUT MARY

先了解您,
再谈规划。

Understanding you.
Before planning ahead.

Mary Guan拥有多年国际贸易、企业经营及金融服务经验,职业经历横跨商业管理、客户服务及加拿大保险与投资领域。

Mary Guan brings experience across international trade, business operations and financial services, including business management, client service and Canadian insurance and investments.

Mary早年学习国际贸易,拥有多年跨国贸易及企业经营经验。她曾参与亚洲、欧洲、澳大利亚及北美等多个国际市场的进出口业务,涉及工业原材料、纸张、纺织服装及其他商品,并积累了丰富的商业谈判、市场开发、企业运营及跨境业务经验。

Mary has an educational background in International Trade and extensive experience in international business and entrepreneurship. Her career has included import and export activities across Asia, Europe, Australia, and North America, involving industrial raw materials, paper products, textiles, apparel, and other goods. Through these experiences, she developed practical expertise in business negotiations, market development, business operations, and cross-border trade.

这些经历让她对企业经营、经济周期、现金流管理及长期财务决策有切身理解。自2016年进入加拿大金融服务行业以来,她持续为个人、家庭及企业主提供保险与财务规划相关服务。

These experiences inform her understanding of business operations, economic cycles, cash flow and long-term financial decisions. Since entering Canadian financial services in 2016, she has served individuals, families and business owners in insurance and financial planning-related matters.

Mary持有安大略省人寿及健康保险代理人执照,并持续参加专业培训与继续教育。她重视充分的需求分析,结合商业经验与金融服务知识,提供审慎、清晰、以客户长期利益为中心的规划建议。

Mary holds an Ontario life and health insurance agent licence and participates in professional training and continuing education. She emphasizes needs analysis and draws on business experience and financial services knowledge to provide clear, considered planning guidance focused on clients’ long-term interests.

Planning for today, with tomorrow in mind.

了解我们的服务理念 ↗Discover our approach ↗
03 / OUR APPROACH

以客户长期利益为中心

Client-Centered Financial Planning

“一份合适的保险规划,不仅要满足今天的需要,也应充分考虑未来的变化。”

“A suitable insurance plan should address today’s needs while taking future changes into account.”

Planning for today, with tomorrow in mind.

01

充分了解需求及财务目标

Understand needs and financial goals

02

重视长期保费与现金流的可持续性

Prioritize sustainable premiums and cash flow

03

根据实际情况评估投资风险

Assess investment risk in context

04

平衡保障、资产增长与资金流动性

Balance protection, growth and liquidity

05

定期检视现有安排

Review existing arrangements regularly

06

以客户利益为先,而非单纯以产品销售为导向

Put client interests ahead of product sales

04 / FINANCIAL EDUCATION

金融知识,帮助理解选择

Knowledge to help you understand your choices

以下为计划中的主题,内容筹备中,敬请期待。

These are planned topics. Articles are being prepared and are not yet published.

买得起的保险,就一定适合你吗?

Is insurance suitable simply because you can afford it?

筹备中Coming soon

Segregated Funds与Mutual Funds有什么不同?

How do segregated funds and mutual funds differ?

筹备中Coming soon

RRSP在71岁时需要注意什么?

What happens to an RRSP at age 71?

筹备中Coming soon

年金如何帮助规划退休收入?

How can annuities support retirement income planning?

筹备中Coming soon

企业主为什么需要提前考虑财富传承?

Why should business owners plan their legacy early?

筹备中Coming soon
05 / LET'S CONNECT

预约咨询,
从一次清晰的对话开始。

Book a Consultation.
Start with a conversation.

请通过电话或邮件联系Mary,说明咨询主题和方便联系的时间;具体时段由双方确认,此处不代表即时预约成功。
请勿发送SIN、出生日期、保单号码、银行账户、详细资产或医疗健康资料。需要时将另行安排适当的资料提交渠道。

Contact Mary by phone or email with your topic and preferred contact times. Your appointment is confirmed only after mutual agreement; this is not an instant booking system.
Do not send a SIN, date of birth, policy number, bank details, detailed financial assets or medical records. An appropriate submission channel can be arranged if needed.

所在地区LOCATIONToronto, Ontario, Canada服务范围:安大略省全省Service area: across Ontario
STAY CONNECTED

微信联系 · 视频号分享

Connect on WeChat. Follow along.